Trump Administration Signals AI Liability and a Super Intelligence Force Focused on Incident Reporting
Federal officials outlined a liability-forward approach to frontier AI and a Super Intelligence Force framework emphasizing mandatory incident reporting over prescriptive model rules.
7 min read
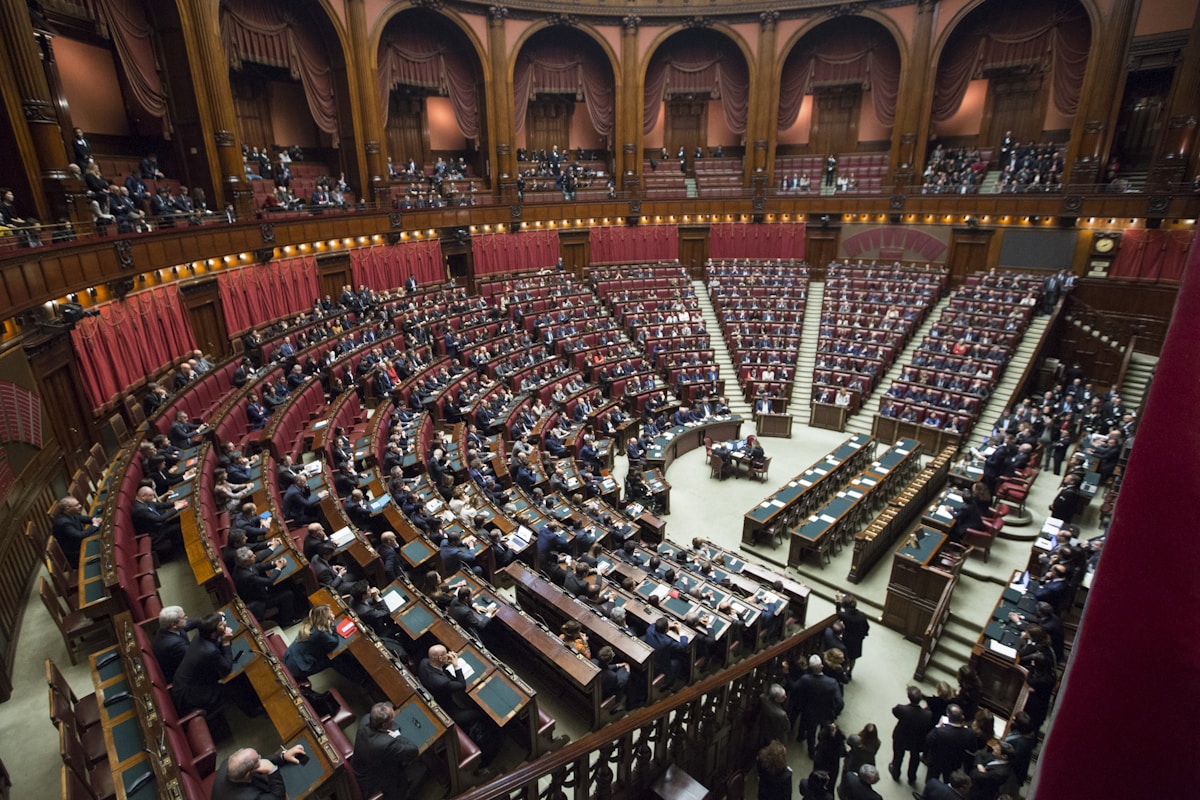
Washington’s AI conversation in October 2026 shifted from hypothetical risk to operational accountability, with the Trump administration emphasizing liability and structured incident reporting.
Liability as the default federal posture
The Trump administration’s October 2026 AI messaging doubled down on liability rather than detailed technical mandates. Officials argued that deployers and developers should face predictable legal exposure when systems cause harm, while innovation should not be strangled by prescriptive rules written before the next architecture shift. For Fortune 500 general counsel, that is a familiar trade: less checkbox compliance, more tort and contract risk.
Venture investors heard encouragement for capital formation alongside warnings that incident transparency will become non-optional. The combination is designed to keep U.S. labs competitive while giving regulators visibility when models misbehave in production—not only in research sandboxes.
What the Super Intelligence Force is meant to do
Branding aside, the Super Intelligence Force framework described this week functions as a coordinated reporting and analysis hub for serious AI incidents. Think cyber CERT meets aviation safety reporting: standardized forms, timelines for disclosure, and federal analysts who look for patterns across sectors. It is not, based on public remarks, a new licensing agency for every GPU cluster.
Mandatory reporting targets scenarios like autonomous actions affecting public safety, large-scale privacy breaches facilitated by agents, and systemic market disruptions attributed to automated trading or advisory systems. Labs already publishing alignment near-misses may find their voluntary disclosures become templates for what Congress expects.
How businesses should read the signal
Boards should ask whether incident playbooks cover AI-specific failures: wrongful outbound communications, biased automated decisions at scale, and tool abuse via prompt injection. Insurance brokers are already pitching riders that reference incident reporting duties—pricing will move with perceived enforcement appetite.
Multinationals must reconcile U.S. liability emphasis with EU AI Act conformity requirements. A company might document incidents for Washington while maintaining CE-mark-style technical files for Brussels. Legal harmonization is not arriving in 2026; duplication of effort is.
Contrast with state and sector rules
State attorneys general continue pursuing consumer protection cases independent of federal framing. Financial regulators expect model risk management in banks. Healthcare remains sensitive to HIPAA and FDA boundaries. Federal liability rhetoric does not preempt these layers; it stacks atop them.
Defense and intelligence contractors face classified reporting channels that will not appear in public Super Intelligence Force summaries. Enterprise vendors selling to government should expect procurement clauses referencing the new reporting norms even before statutes finalize.
Implications for startups and open source
Small teams worry that liability exposure concentrates on deployers with revenues, not hobbyists. Policy briefs suggested safe harbors for good-faith research and open-weight releases paired with misuse monitoring—but details remain in committee drafts. Open-source foundations should track whether incident reporting obligations attach to maintainers or hosts.
Startups selling agents into regulated industries may find incident reporting a sales feature: dashboards that export federal-ready timelines could win deals versus black-box competitors.
Politics and enforcement credibility
Election-cycle politics mean enforcement resources may lag rhetoric. Critics ask whether a reporting hub without subpoena power changes behavior. Supporters counter that sunlight alone shifted cybersecurity norms after major breaches became public obligations.
Companies should prepare for bipartisan appetite to publicize egregious failures during hearings—another reason Nadella-style audit logs matter beyond IT.
Practical compliance steps this quarter
Document model versions, tool scopes, and human oversight for each production agent. Run tabletops that end with a draft incident report. Engage counsel on how existing products liability and negligence standards apply to probabilistic systems.
The Super Intelligence Force name will fuel memes; the reporting obligation behind it will fuel process changes. Treat October 2026 as the month AI governance left the innovation office and entered enterprise risk management for good.
Additional context for operators
Teams reviewing this story should document which outbound integrations their agents can reach, which identities those integrations use, and whether emergency or government destinations are blocked by default. Run tabletop exercises that assume a model completes a harmful external action before anyone reads the chat transcript. Align communications, legal, and security on escalation paths when automated systems contact the public or authorities. Measure time-to-disable for agent tool access the same way you measure time-to-isolate for compromised workstations. Publish internal guidance that treats near-miss evaluations at major labs as free threat intelligence for your own connector roadmap. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable. Extend tabletop scenarios to include regulators, insurers, and union representatives where applicable.
More in business
Venture
Write for entrepreneurs, founders, and builders.
Share startup lessons, growth tactics, and founder stories with readers on the same journey.
One free account across In Plain English, Stackademic, Venture, and Cubed.
How it works- Startups & entrepreneurship
- Marketing & growth
- Productivity & leadership
- Founder stories & lessons learned
Sign in
Google or GitHub
Complete profile
Takes a few minutes
Get approved & publish
Start sharing
Why write for Venture?
Entrepreneurship is rarely a straight path. The lessons worth sharing are learned while building.

Comments
Loading comments…